This blog is based on our analysis — Facility Management Market, United Kingdom, 2025–2032 — authored by John Raspin, Partner & Global Head of Growth Opportunity Analytics, Frost & Sullivan.
Facility management (FM) services help organizations maintain safe, efficient, and productive workplaces across commercial buildings, industrial facilities, healthcare sites, and public infrastructure. As workplace needs continue to change, FM providers are expected to deliver more flexible, integrated, and efficient services.
Today, the UK FM industry faces growing pressure. Economic uncertainty, rising operating costs, labor shortages, and changing workplace models are challenging traditional service delivery. At the same time, demand for sustainability, workplace flexibility, smart building operations, and integrated FM services continues to grow across sectors.
With the UK FM industry projected to reach $56.41 billion by 2032 at a CAGR of 3.1%, providers that strengthen digital operations, integrated service delivery, and sustainability capabilities will be better positioned to improve efficiency, support evolving customer needs, and drive long-term growth.
Is Your FM Strategy Ready for What’s Next?
Explore the market shifts, strategic imperatives, and growth opportunities shaping the future of facility management.
Download the Full Analysis
The transformation is clear. Which strategies will you adopt to lead the facility management landscape?
Listen to our latest podcast for UK facility management strategies.
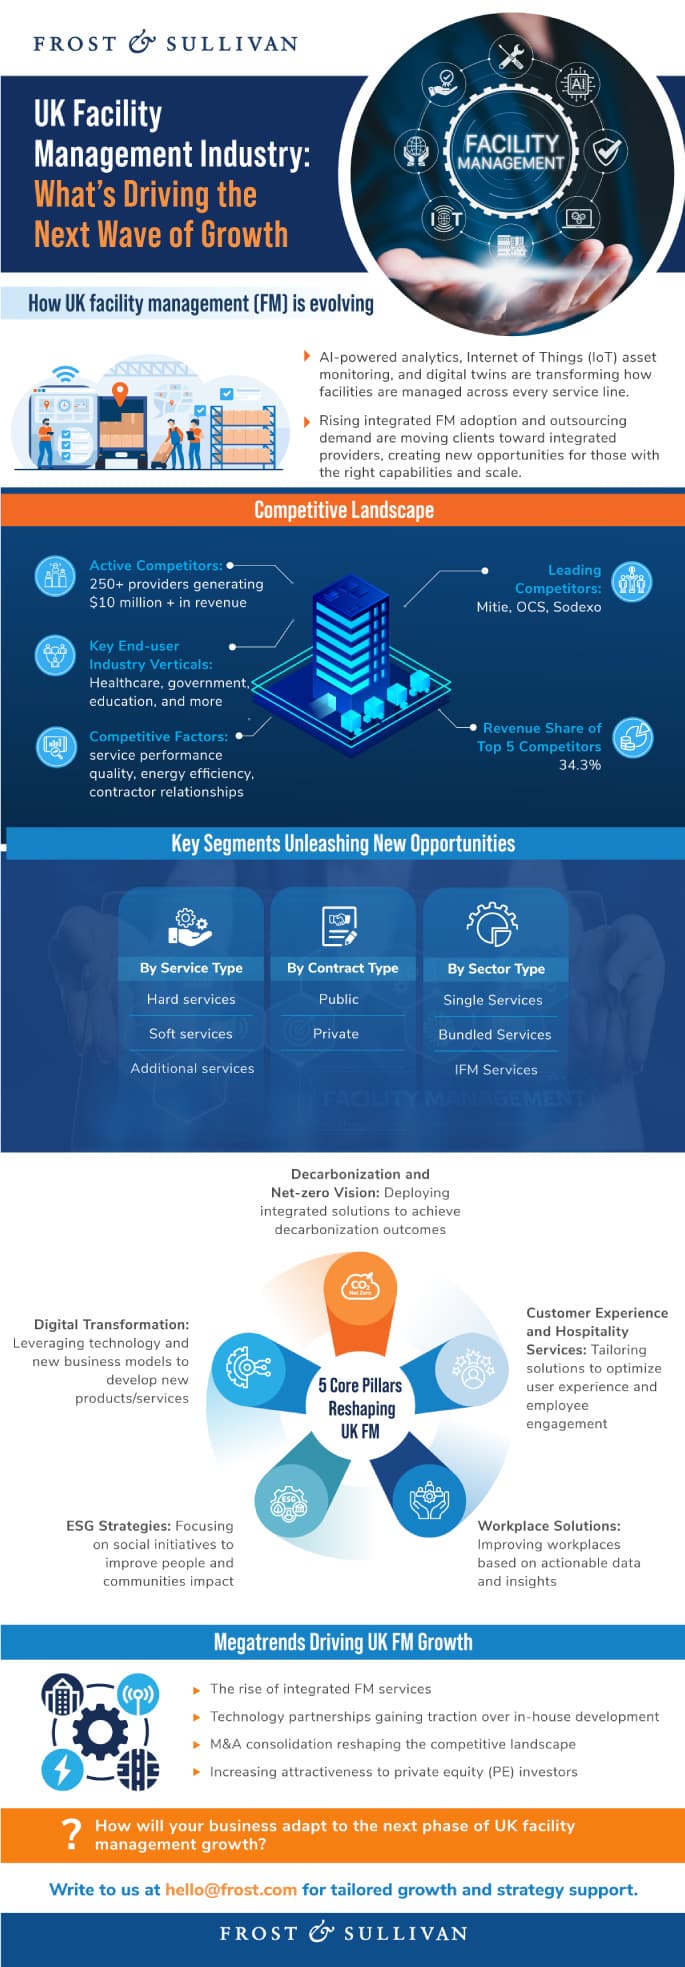
Top 3 Strategic Imperatives Reshaping the UK FM Industry
- Geopolitical disruptions
Brexit, COVID-19, supply chain shocks, inflation, and global conflicts have created ongoing uncertainty across the UK FM industry. These disruptions continue to pressure costs, strain supply chains, and impact workforce availability, making stable margins harder to maintain.
- Transformative megatrends
Shifts in workplace models, rising sustainability expectations, and changing workforce behaviour are reshaping the FM service delivery. Hybrid work and higher demand for flexibility are also pushing providers to rethink service design and focus more on user experience.
- Internal challenges
Slow adoption of new operating and service models has led to commoditization and weaker margins for many providers. At the same time, slower growth in many customer segments is forcing the industry to move beyond traditional approaches and build more differentiated, value-driven services.
Growth Avenues Across the UK Facility Management Value Chain
Leading Facility Management Companies in the UK to Watch
- Mitie
Mitie holds a strong position across cleaning, security, and technical services and has grown steadily through organic expansion and acquisitions. Its 2025 acquisition of Marlowe plc reflects a clear move into compliance, testing, inspection, and certification, extending the business beyond its traditional FM footprint. - Compass Group
The acquisition of CH&CO in early 2024 strengthened Compass’s position in food services, with the segment delivering solid growth and profitability through 2024 and 2025. Compass also placing greater emphasis on non-food FM across its brands, including 14Forty and LSS. - CBRE
The UK remains CBRE’s largest FM market in Europe, with consistent growth across IFM and hard FM. The 2025 acquisition of Industrious led to the formation of a new Building Operations and Experience division, with dedicated leadership and a broader operational remit.
Megatrends Accelerating Innovation in Facility Management
- Business Productivity, Resilience, and Risk: Helping organizations improve efficiency, reduce risk, and strengthen operational resilience.
- User Experience and Human Touch: Creating workplace environments that improve occupant satisfaction and engagement.
- AI and Robotics: Using automation, analytics, and intelligent systems to improve facility operations.
- Sustainability and ESG: Advancing energy efficiency, decarbonization, and social impact strategies.
- Partnerships and Collaboration: Expanding capabilities through technology and service partnerships.
- Selling Outcomes: Moving toward performance-based and efficiency-driven service models.
- Internet of Things (IoT) and Cloud Services: Improving visibility and decision-making through connected building technologies and cloud platforms.
- Health and Wellness: Supporting healthier workplaces focused on employee wellbeing and productivity.
Barriers Slowing Growth in the UK Facility Management Industry
- Budget and Cost Pressures: Increasing customer price sensitivity due to economic uncertainty and tighter budgets.
- Outsourcing Barriers: Limiting FM outsourcing growth through continued reliance on in-house service delivery in some sectors.
- Margin Pressure and Commoditization: Pressuring profitability through intense price competition and commoditized service offerings.
- Sustainability Investment Gaps: Reducing investment momentum in decarbonization and net-zero initiatives across customer segments.
- Complex Public-sector Procurement: Challenging supplier participation through lengthy and complex public-sector tendering processes.
Emerging Growth Opportunities for UK FM Providers
- Decarbonization and Net-zero Services
The growing focus on decarbonization, energy efficiency, and sustainability is creating new opportunities across the UK FM industry. Organizations are facing increasing pressure to reduce emissions, improve energy performance, and meet evolving reporting requirements across buildings and estates.
To strengthen their position in this space, FM providers are:
- Developing decarbonization strategies covering energy management, emissions monitoring, and carbon reporting.
- Expanding capabilities in renewable energy integration, electric vehicle (EV) fleet optimization, and sustainable building operations.
- Building partnerships and specialist expertise to support long-term net-zero goals.
- Customer Sector Alignment
Customer expectations across the UK FM industry are becoming more sector-specific, increasing demand for tailored services and specialized expertise. Organizations are placing greater value on providers that understand their operational challenges, workplace requirements, and end-user expectations across sectors such as healthcare, education, government, and commercial real estate.
To strengthen customer alignment, FM providers are:
- Developing sector-specific services and value propositions tailored to unique customer needs.
- Aligning sales, delivery, and operational teams around key customer sectors and workplace challenges.
- Strengthening customer engagement strategies through deeper industry expertise and specialized service capabilities.
The Future of Facility Management: Integration, Innovation, and Value Creation
The UK FM industry is moving beyond traditional service delivery as workplace expectations, sustainability priorities, and integrated solutions reshape customer demands and competitive positioning.
The next phase of growth will be shaped by:
- Technology and digital operations improving efficiency, visibility, and decision-making
- Customer alignment and sector expertise strengthening workplace experience and service differentiation
- Sustainability and ESG initiatives accelerating decarbonization and energy management efforts
- M&A activity and partnerships expanding scale, capabilities, and specialized service offerings
As FM becomes more closely tied to business performance, providers will play a greater role in supporting resilience, productivity, and long-term operational goals.
Ready to Lead the Transformation?
- Schedule a Growth Strategy Dialog: Align your growth roadmap with Frost & Sullivan’s Visionary Growth Pipeline™ Dialog.
- Engage with Growth Experts: Co-design AI-enabled, data-driven operating models that scale industry-specific and commercial impact.
- Showcase Your Transformational Leadership: Position your organization as a transformation leader through Frost & Sullivan’s Transformational Growth Leadership platform.
- Join the Growth Council: Collaborate with industry leaders shaping the future of your ecosystem.
- Explore Best Practices Recognition: Be recognized for excellence in growth strategy, execution, and customer impact.
- Benchmark Your Industry Positioning on the Frost Radar™: Benchmark your growth performance and innovation strength against industry competitors.
- Tell Your Story: Accelerate awareness, engagement, and revenue growth through integrated brand and demand generation strategies.
Frequently Asked Questions (FAQs)
What is facilities management in the UK?
Facilities management in the UK involves managing buildings, workplaces, infrastructure, and support services to ensure they remain safe, compliant, efficient, and productive. It covers hard FM services, including maintenance, HVAC, plumbing, and electrical systems, as well as soft FM services such as cleaning, security, catering, and waste management. The industry increasingly uses digital technology and sustainable practices to improve building performance and workplace experience.
What are facility management solutions?
Facility management solutions are services, technologies, and processes that help organizations operate and maintain buildings, assets, and workplaces efficiently. They include maintenance, cleaning, security, catering, space management, energy management, compliance, and workplace services. Digital solutions may also use artificial intelligence, Internet of Things sensors, cloud platforms, and data analytics to automate tasks, anticipate maintenance requirements, reduce operating costs, and improve building performance.
What are the top five facilities management companies in the UK?
Five prominent facilities management companies in the UK are Mitie, CBRE, Sodexo, OCS, and ISS. These companies provide integrated FM services spanning building maintenance, engineering, cleaning, security, catering, workplace experience, energy management, and sustainability. The leading providers vary depending on the ranking criteria, such as UK revenue, market share, contract portfolio, sector coverage, and service capabilities.
What is facilities management in the UK?
Facilities management in the UK involves managing buildings, workplaces, and support services that help organizations operate effectively. It includes hard services such as maintenance and HVAC (heating, ventilation, and air conditioning), and soft services such as cleaning, security, and catering. The industry increasingly focuses on sustainability, digitalization, and integrated service delivery.
What are the 4 pillars of facilities management?
The four pillars of facilities management are people, process, place, and technology. People focus on workplace experience and safety, process on operational efficiency, place on buildings and infrastructure, and technology on digital tools that improve performance, sustainability, and decision-making.