This blog is based on Frost & Sullivan’s recent analysis, Satellite Communication (SATCOM), Earth Observation (EO), and Position, Navigation, and Timing (PNT) Value Chain Analysis, authored by growth expert Wayne Shaw and lead expert Aarthi Kannadoss from the Aerospace & Defense Practice Area.
Executive Summary
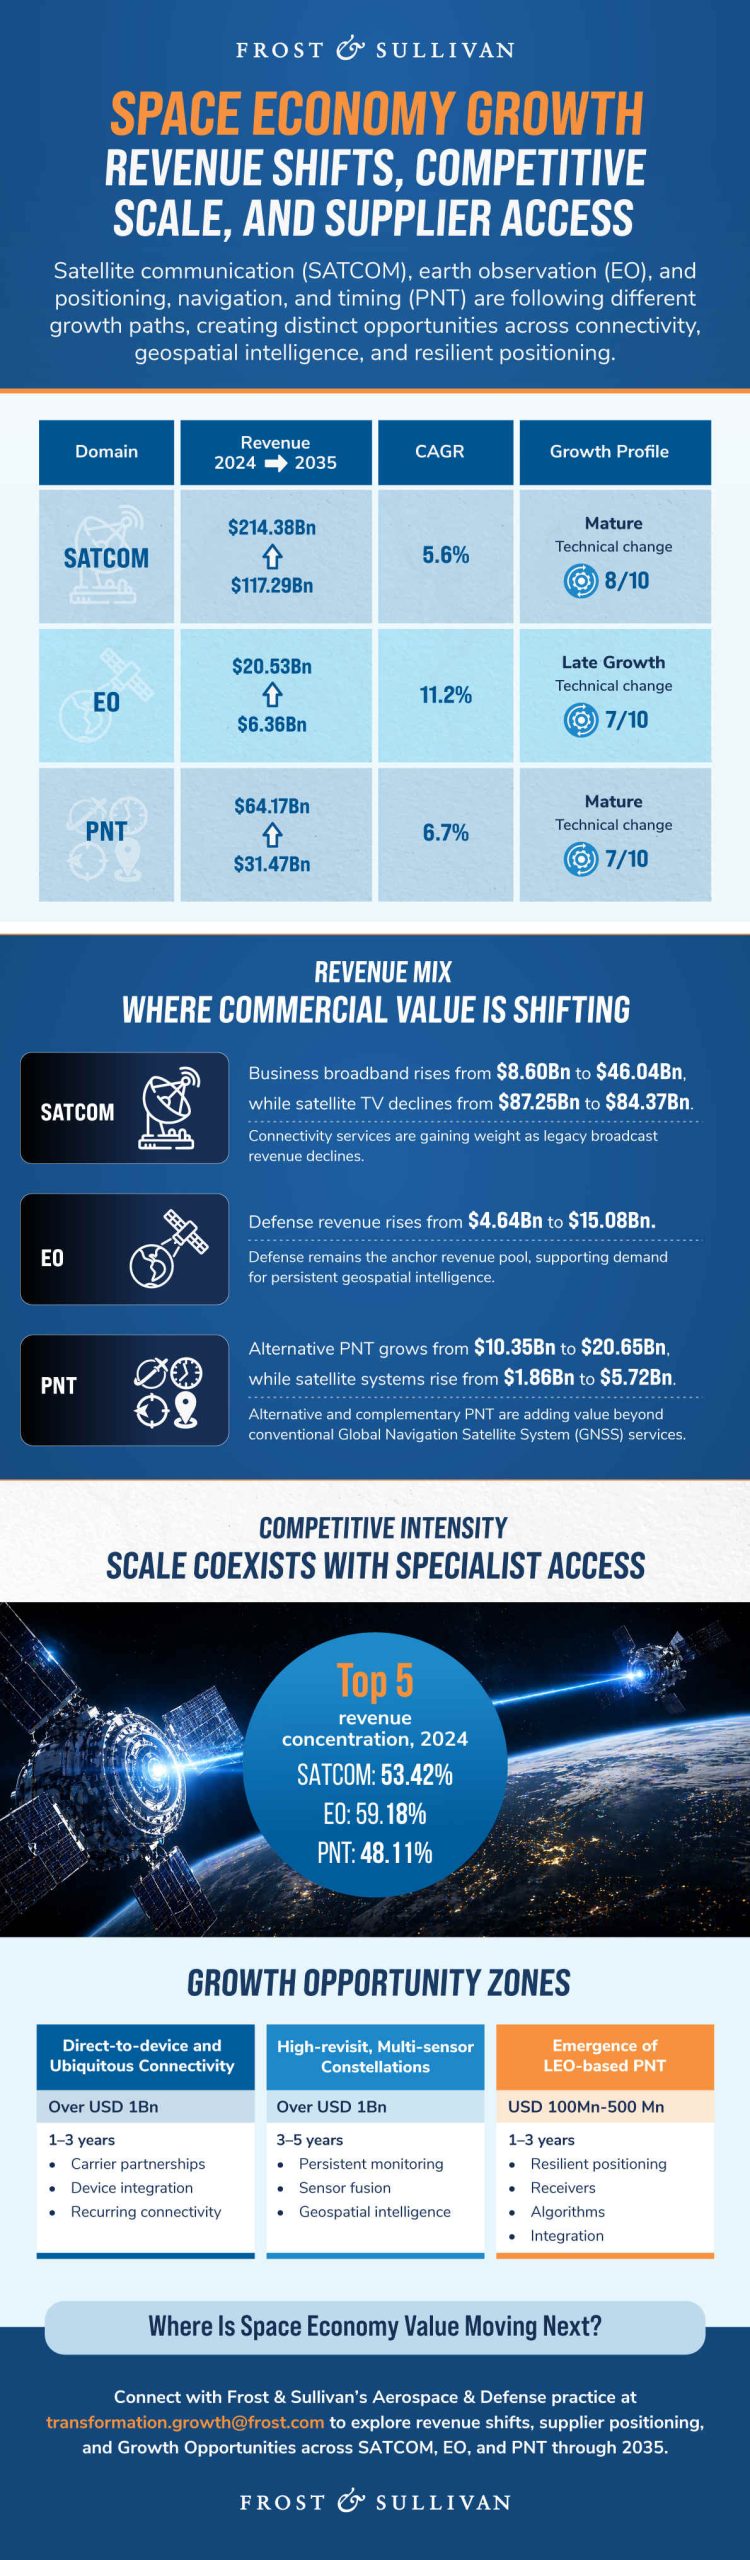
The global space economy is undergoing a structural shift as Low Earth Orbit (LEO) constellations, software-defined architectures, and service-led delivery reshape satellite communication (SATCOM), earth observation (EO), and positioning, navigation, and timing (PNT). SATCOM alone is projected to grow from USD 117.29 billion in 2024 to USD 214.38 billion by 2035. Across the three domains, recurring services, ecosystem integration, and consolidation are placing greater weight on customer access, scalable service delivery, and differentiated supplier capabilities.
Key Takeaways:
- SATCOM convergence is reshaping market access: Non-terrestrial networks (NTNs) and direct-to-device connectivity are increasing the importance of carrier partnerships, interoperability, and service integration.
- EO monetization is moving downstream: Imagery commoditization is shifting value toward geospatial intelligence, recurring analytics, and workflow integration.
- PNT resilience is widening supplier roles: Multi-layer architectures are increasing demand for correction, integration, assurance, and resilient timing beyond conventional Global Navigation Satellite System (GNSS) hardware.
- Scale is raising the entry bar: Integrated platforms are extending ecosystem control, while specialists are retaining positions through software, analytics, and application expertise.
What Are SATCOM, EO, and PNT in the Space Economy?
SATCOM provides connectivity across consumer, enterprise, mobility, and telecom applications. EO uses satellite data to support geospatial intelligence and operational decision-making, while PNT provides positioning, navigation, timing, and synchronization across mobility, defense, telecom, and critical infrastructure.
According to Frost & Sullivan, SATCOM, EO, and PNT are developing beyond standalone space assets as software, data, services, and applications take a larger role across their value chains. This is expanding how providers create commercial value and differentiate across the broader space ecosystem.
Why Is Value Chain Positioning Gaining Importance Across the Space Economy?
Technology shifts are changing how participants compete across SATCOM, EO, and PNT. LEO deployment, software-defined infrastructure, cloud integration, advanced analytics, and resilient positioning architectures are bringing traditionally separate parts of the value chain closer together. At the same time, partnerships, acquisitions, and vertical integration are strengthening control over infrastructure, services, and customer relationships.
Where Is Your Next Space Growth Opportunity?
Assess how SATCOM, EO, and PNT value-chain shifts are reshaping supplier positioning and commercial growth through 2035.
[Download the Strategic Analysis]
Competitive concentration is reinforcing this shift. In 2024, the top five participants accounted for 53.42% of SATCOM revenue, 59.18% of EO revenue, and 48.11% of PNT revenue. Scale is supporting broader ecosystem positions, while specialist providers are retaining entry points through software, analytics, integration, and vertical-specific capabilities.
Strategic Imperatives Across SATCOM, EO, and PNT
- SATCOM – Customer Value Chain Compression, Disruptive Technologies, and Industry Convergence: Operators are moving closer to end users through managed services. LEO, high-throughput satellites, and software-defined architectures are improving network flexibility, while partnerships with mobile operators and device ecosystems are extending direct-to-device connectivity.
- EO – Geopolitical Chaos, Innovative Business Model, and Competitive Intensity: Sovereign intelligence requirements are increasing demand for persistent EO capabilities. Raw imagery commoditization is also pushing providers toward subscriptions, analytics, and vertical services, making workflow integration a stronger source of differentiation.
- PNT – Innovative Business Model, Disruptive Technologies, and Industry Convergence: Service-based models are gaining ground as multi-constellation, alternative, and LEO-enabled architectures improve resilience. Integration with mobility, telecom, and critical infrastructure is expanding the commercial role of assured positioning and timing.
Frost & Sullivan Perspective
According to Frost & Sullivan, the common commercial thread across these Strategic Imperatives is a shift in value capture from standalone space assets toward recurring services, stronger customer access, and control of key ecosystem interfaces. Integrated providers are gaining leverage where scale and platform breadth support end-to-end delivery, while specialists are retaining defensible roles in analytics, assured PNT, software-defined infrastructure, and vertical applications. Supplier relevance depends more on how effectively these capabilities integrate with larger service ecosystems and customer workflows.
Have you evaluated your organization’s technology and digital capabilities to support future growth initiatives?
Growth Drivers Expanding Competitive Positioning Across the Space Economy
| Domain | Growth Signals | Commercial Positioning |
| SATCOM | Resilient government communications, LEO and high-throughput satellite deployment, mobility demand, and lower terminal costs are supporting broader adoption. | Multi-orbit services, managed connectivity, ground software, and direct-to-device ecosystems are creating routes to value beyond capacity provision. |
| EO | High-revisit geospatial demand, smaller satellites, advanced sensors, and AI-enabled analytics are improving monitoring frequency and cost economics. | Commercial value is moving downstream into geospatial intelligence, continuous monitoring, subscriptions, and vertical-specific applications. |
| PNT | Autonomy, unmanned systems, telecom timing, and critical-infrastructure resilience are raising demand for precise and assured positioning. LEO and alternative PNT are adding new layers of redundancy. | Multi-constellation receivers, correction services, sensor fusion, resilient timing, and assured PNT are creating differentiated positions beyond conventional GNSS hardware. |
Competitive structure shows how differently these opportunities are being captured. The top five participants account for 53.42% of SATCOM revenue, 59.18% of EO revenue, and 48.11% of PNT revenue in 2024. Starlink is using LEO scale and vertical integration to strengthen its SATCOM position, while Maxar leads EO revenue with 25.3%, supported by its position across imagery and geospatial intelligence. Hexagon leads PNT with 23.1%, with acquisitions extending its positioning capabilities across GNSS, autonomy, and mission-critical applications.
Across the broader space economy, scale is supporting wider ecosystem control, but specialist positions remain viable where software, analytics, resilient infrastructure, or application expertise offer clear differentiation.
Business Implication: Growth is creating two distinct competitive paths: broader platforms can capture value across multiple layers of the ecosystem, while specialists can build defensible positions around high-value capabilities and domain-specific applications.
How well do you think your organization is positioned to capitalize on emerging growth opportunities in your industry?
Top Three Growth Opportunities Converting Space Capabilities into Commercial Value
- Direct-to-device (D2D) and Ubiquitous Connectivity
D2D is reducing dependence on dedicated terminals by connecting smartphones, vehicles, and other devices directly to satellites. Apple-Globalstar and emerging services from Starlink, AST SpaceMobile, and Lynk illustrate the growing connection between satellite, telecom, and device ecosystems.
Business implication: The more than USD 1 billion five-year opportunity is shifting revenue toward carrier partnerships, device integration, and recurring connectivity services rather than bandwidth alone.
- Proliferation of High-revisit, Multi-sensor Constellations
Dense LEO constellations are combining optical, synthetic aperture radar, hyperspectral, and thermal sensing to move EO from periodic imagery toward persistent monitoring and faster change detection.
Business implication: With more than USD 1 billion in five-year potential, commercial value is concentrating around sensor fusion, rapid data delivery, and continuous geospatial intelligence for defense, infrastructure, agriculture, and climate applications.
3. Emergence of LEO-based PNT
LEO-based PNT is adding stronger signals, faster geometry changes, and greater resilience as a complementary layer to GNSS and terrestrial positioning. Xona and Iridium are among the companies advancing LEO-enabled positioning and timing capabilities identified in the analysis.
Business implication: The USD 100 million to USD 500 million five-year opportunity creates positions across receivers, algorithms, signal processing, and integration, particularly where resilient and assured PNT carries greater value.
Future Outlook: Integrated Services Are Defining the Next Phase of Space Growth.
Through 2035, SATCOM, EO, and PNT are becoming more closely connected with terrestrial networks, software platforms, analytics, and end-user applications. Service models are also changing as managed connectivity, subscription analytics, and resilient positioning give providers more recurring touchpoints with customers.
Three shifts are defining the commercial landscape:
- Managed services are taking a larger role in revenue models, reducing dependence on one-time capacity or data sales.
- Space-terrestrial integration is bringing telecom, cloud, mobility, and satellite providers into shared service ecosystems.
- Specialist expertise is retaining value where geospatial intelligence, resilient PNT, or application-specific performance remains difficult to replicate.
According to Frost & Sullivan, value-chain position is carrying greater commercial weight alongside technology ownership. Integrated platforms are using scale and customer reach to participate across multiple service layers, while specialists are competing through technical depth, domain expertise, and application relevance.
How are you actively monitoring the space economy trends and disruptions that could affect your organization’s growth potential?
Ready to Lead the Transformation?
- Schedule a Growth Strategy Dialog: Align your growth roadmap with Frost & Sullivan’s Visionary Growth Pipeline™ Dialog.
- Engage with Growth Experts: Co-design AI-enabled, data-driven operating models that scale industry-specific and commercial impact.
- Showcase Your Transformational Leadership: Position your organization as a transformation leader through Frost & Sullivan’s Transformational Growth Leadership platform.
- Join the Growth Council: Collaborate with industry leaders shaping the future of your ecosystem.
- Explore Best Practices Recognition: Be recognized for excellence in growth strategy, execution, and customer impact.
- Benchmark Your Industry Positioning on the Frost Radar™: Benchmark your growth performance and innovation strength against industry competitors.
- Tell Your Story: Accelerate awareness, engagement, and revenue growth through integrated brand and demand generation strategies.
Connect with our growth experts at [email protected].
FAQs
1. What is driving growth across the space economy?
LEO deployment, software-defined infrastructure, advanced analytics, and demand for resilient connectivity and positioning are driving growth across SATCOM, EO, and PNT.
2. How is SATCOM changing within the space economy?
SATCOM is moving beyond wholesale capacity toward managed connectivity, multi-orbit services, and direct-to-device applications. Partnerships with telecom operators and device ecosystems are also bringing satellite services closer to mainstream connectivity workflows.
3. Why is geospatial intelligence gaining value in earth observation?
Raw imagery commoditization is pushing EO providers toward geospatial intelligence, sensor fusion, and continuous monitoring embedded in customer workflows.
4. Why is resilient PNT becoming more important?
Jamming, spoofing, autonomous mobility, and critical-infrastructure requirements are increasing demand for positioning and timing that does not depend on a single GNSS source. Multi-constellation receivers, sensor fusion, alternative signals, and LEO-based PNT are supporting more resilient architectures.
5. What is changing in the Satellite Communication Market?
The Satellite Communication Market is shifting toward LEO and multi-orbit architectures, managed services, satellite-terrestrial convergence, and direct-to-device connectivity. These developments are increasing the importance of software, service integration, and ecosystem partnerships alongside satellite capacity.
6. What is shaping growth in the Earth Observation Market?
Higher-revisit constellations, advanced sensors, AI-enabled analytics, and persistent monitoring are driving growth in the Earth Observation Market. Providers are moving from raw imagery toward recurring analytics and vertical-specific services.
7. What is changing in the Position Navigation and Timing Market?
The Position Navigation and Timing Market is moving toward more resilient and layered architectures. GNSS correction services, alternative PNT, multi-sensor fusion, and LEO-based positioning are broadening the technology mix supporting autonomy, telecom, defense, and critical infrastructure.
8. How are LEO satellites influencing SATCOM, EO, and PNT?
LEO satellites are supporting lower-latency connectivity in SATCOM, higher revisit rates in EO, and stronger complementary positioning signals in PNT. Their growing role is also increasing demand for software-defined networks, ground infrastructure, data processing, and interoperable service ecosystems.