This blog is based on Frost & Sullivan’s analysis, GCC Plastic Circular Economy, 2025–2030, authored by Prasad Patil from the Chemicals, Materials, and Nutrition Practice Area.
Executive Summary
The Gulf Cooperation Council (GCC)’s plastic ecosystem is shifting toward greater circularity as regulatory action, infrastructure investment, and industry participation expand across Saudi Arabia, the United Arab Emirates (UAE), and Oman. Despite low recycling rates and gaps in collection, sorting, and processing, the convergence of waste management, recycling, and petrochemicals is creating new opportunities across advanced recycling, circular polymers, and integrated value chains.
Key Takeaways
- Low recycling rates are creating significant value pools across collection, sorting, recycling, and circular material production.
- Saudi Arabia, the UAE, and Oman are progressing at different levels of circularity, creating distinct infrastructure and growth opportunities across the three markets.
- Advanced recycling and circular polymer solutions are expanding the opportunity landscape, particularly for hard-to-recycle plastics and recycled-content applications.
The Gulf Cooperation Council (GCC) has established strengths in plastics production, petrochemicals, and polymer manufacturing, but its downstream plastic waste ecosystem remains comparatively underdeveloped. Low recycling rates, fragmented collection and source segregation, and limited recovery capabilities are resulting in significant value loss through landfilling, inefficient processing, and exports.
As Saudi Arabia, the UAE, and Oman expand circular-economy policies, waste infrastructure, and industry participation, opportunities are emerging across collection, sorting, mechanical and advanced recycling, and higher-value material recovery. The strategic opportunity is to connect the GCC’s existing polymer capabilities with a more integrated downstream circular plastics ecosystem.
Listen to our podcast episode on the Growth Opportunities Shaping GCC Plastic Circular Economy.
What Is the GCC Plastic Circular Economy?
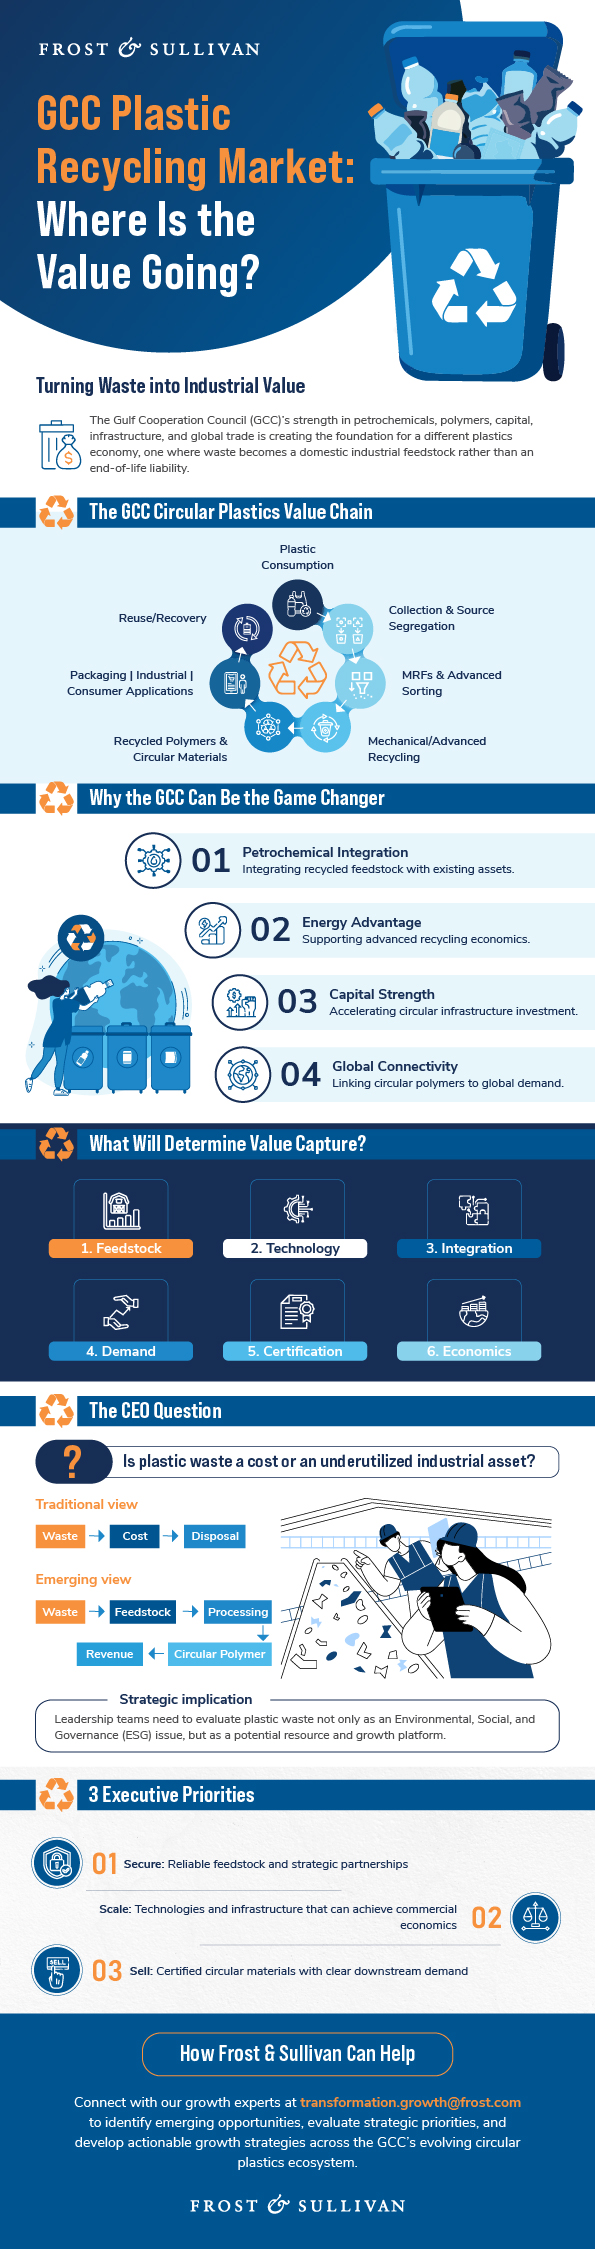
The GCC plastic circular economy encompasses the collection, segregation, sorting, recycling, and recovery of plastic waste, connecting waste-management systems with recyclers, petrochemical producers, polymer manufacturers, converters, and brand owners.
The ecosystem includes material recovery facilities (MRFs), mechanical and advanced recycling, waste-to-energy (WtE), and refuse-derived fuel (RDF) pathways. Across Saudi Arabia, the UAE, and Oman, differences in collection, sorting infrastructure, feedstock quality, and recycling capabilities are shaping the development of circular plastics.
Why the GCC Has a Structural Advantage in Circular Plastics
The GCC’s circular plastics opportunity is being supported by strengths that extend well beyond its waste-management ecosystem. The region combines deep capital availability, established petrochemical infrastructure, polymer manufacturing expertise, industrial clusters, and access to global trade routes, creating a strong foundation for scaling circular plastics.
These advantages are strengthening the GCC plastic recycling market by enabling investment in integrated collection, sorting, and advanced recycling systems while connecting recovered feedstock with established polymer and conversion ecosystems. The region’s existing industrial capabilities are also enabling circular-material solutions to be integrated more closely with downstream manufacturing and export networks.
This positioning is creating an opportunity for the GCC to evolve from a major producer of virgin polymers into a regional hub for circular polymers. As demand for recycled content and traceable materials increases, the opportunity is extending beyond domestic waste management toward commercially viable circular-material platforms that can serve both regional and international markets.
Strategic Imperatives Reshaping the GCC Plastic Circular Economy
- Transformative Megatrends
Regulatory momentum, sustainability commitments, rising plastic consumption, and pressure to reduce virgin polymer dependence are accelerating the GCC’s transition toward circularity. As the focus shifts from compliance toward value creation, investment in recycling infrastructure, advanced technologies, and solutions for hard-to-recycle plastics is gaining importance.
- Industry Convergence
The boundaries between petrochemicals, waste management, recycling, and polymer production are increasingly converging, creating opportunities for partnerships, joint ventures, and public-private models across the value chain. Vertical integration, from feedstock collection to recycled polymer production, is also emerging as a key differentiator.
- Competitive Intensity
Growing participation from start-ups, global recyclers, and regional conglomerates is increasing competition across Saudi Arabia, the UAE, and Oman. As the ecosystem develops, differentiation is shifting toward scale, integration, recycled-polymer quality, consistency, certification, and technology and business-model innovation.
Reflecting on these imperatives, Prasad Patil, Consultant, Chemicals and Materials, Frost & Sullivan, observes: “The GCC plastic circular economy is being shaped by coordinated government mandates, rising capital deployment, and deeper collaboration across the plastics value chain. Investments in sorting infrastructure, MRFs, segregation systems, and advanced recycling are addressing capacity gaps, while policy targets are creating stronger demand signals for recycled polymers. As petrochemical producers, recyclers, waste-management companies, and technology providers increasingly collaborate, scale, integration, and the ability to deliver high-quality certified recycled materials are becoming critical competitive differentiators.”
Country-level Comparison: GCC Plastic Circular Economy Market
The three markets are at different stages of circularity, creating distinct investment priorities: Saudi Arabia offers scale, the UAE shows stronger ecosystem momentum, and Oman presents opportunities to build foundational collection and recycling capabilities.
| Parameter | Saudi Arabia | UAE | Oman |
| Plastic waste generated | 5.8–6.6 million metric tons (MT) | 1.1–1.2 million MT | 0.55–0.60 million MT |
| Plastic waste collected for recycling | 8% | 12% | 13% |
| Recycled plastic | 6% | 10% | 6% |
| Recycling outlook by 2030 | 12%–22% | 15%–25% | 10%–21% |
| Ecosystem Characteristics | Large waste volumes, strong industrial base, developing recycling infrastructure | More developed collection initiatives, recycling investments, and policy activity | Emerging recycling ecosystem with significant infrastructure and quality gaps |
| Key Development Areas | Collection, segregation, advanced sorting, recycling capacity | Sorting, MRF capacity, EPR implementation, advanced recycling | Source segregation, sorting, recycling quality, domestic utilization |
| Primary Opportunity Areas | Large-scale feedstock recovery and recycling | PET recovery, advanced recycling, circular material platforms | Feedstock capture, recycling infrastructure, higher-value applications |
Source: Frost & Sullivan analysis.
Saudi Arabia offers the largest feedstock opportunity because of its substantial plastic waste volumes and established petrochemical ecosystem. The UAE is showing stronger momentum across recycling initiatives and infrastructure development, while Oman presents opportunities to strengthen an emerging ecosystem and reduce value leakage from landfilling and exports.
Key Challenges Influencing Growth
Despite increasing momentum, several structural challenges continue to constrain plastic circularity across the GCC:
- Fragmented collection and weak source segregation limit the availability of clean, consistent feedstock.
- Limited sorting and recycling infrastructure restricts recovery capacity and material quality.
- Inconsistent recycled-material quality constrains adoption in higher-value applications.
- Regulatory and policy gaps can limit investment certainty and recycled-content demand.
- Limited data transparency makes it difficult to accurately assess waste flows and identify investment priorities.
- Competition from virgin polymers can affect the price competitiveness and margins of recycled materials.
Top Three Growth Opportunities
- Integrated Collection and Advanced Sorting
The development of integrated collection, source segregation, MRFs, AI-enabled sorting, and preprocessing is creating opportunities to improve feedstock availability and recovery efficiency across the GCC.
- Advanced Recycling
Chemical recycling technologies, including pyrolysis and depolymerization, are gaining relevance for mixed, multilayer, contaminated, and other hard-to-recycle plastics that are difficult to process through conventional mechanical recycling.
- Circular Polymer Solutions
The development of recycled-content resins, recyclable-by-design packaging, and integrated material platforms is creating opportunities to connect recovered plastic feedstock with regional and export markets, strengthening the commercial potential of circular economy plastics.
According to Frost & Sullivan
The strongest growth opportunities in GCC plastic circularity are emerging where infrastructure, technology, and downstream demand are integrated across the value chain. Companies that secure reliable feedstock, scale advanced processing, and develop certified recycled polymers will be better positioned to capture value as the GCC moves from fragmented recycling initiatives toward commercially viable circular ecosystems.
Competitive Environment: From Recycling Capacity to Circular Integration
The GCC’s competitive landscape is being shaped by companies expanding beyond conventional recycling into advanced recycling and circular polymer production. SABIC is scaling its TRUCIRCLE™ portfolio, including certified circular polymers produced from difficult-to-recycle plastics.
Meanwhile, Aramco, in partnership with SABIC and TotalEnergies, has demonstrated the conversion of plastic-waste-derived oil into ISCC+ certified circular polymers in Saudi Arabia, helping establish a domestic advanced-recycling value chain. These initiatives are signaling a shift toward integrated, technology-driven models that connect waste recovery with high-value polymer production.
What Industry Leaders Should Watch
The evolution of the GCC plastic circular economy raises several strategic considerations:
- Feedstock availability: Can collection and segregation systems provide sufficient volumes of consistent-quality plastic waste?
- Technology selection: Where should mechanical recycling end and advanced recycling begin?
- Infrastructure integration: Can MRFs, preprocessing, recycling, and polymer production operate as connected systems?
- Demand creation: How quickly can recycled polymers gain acceptance in packaging and other higher-value applications?
- Partnership models: Which combinations of petrochemical companies, recyclers, waste managers, municipalities, and brand owners can accelerate scale?
- Regulatory alignment: Can policies and standards create consistent incentives across the GCC?
These questions will increasingly influence investment decisions and competitive positioning across the circular plastics ecosystem.
The Road Ahead for Plastic Circularity in the GCC
The GCC’s plastic circular economy is expected to become more integrated as investments in collection, sorting, recycling, and circular material infrastructure expand. The convergence of petrochemicals, waste management, recycling, and polymer production is creating stronger links between recovered feedstock and downstream applications.
As Saudi Arabia, the UAE, and Oman strengthen their respective ecosystems, competitive differentiation is likely to center on feedstock access, technology, integration, recycled-material quality, and end-market linkages. The next phase will increasingly focus on converting recovered plastics into reliable industrial feedstock and higher-value circular products.
Frequently Asked Questions (FAQs)
1. What is the plastic circular economy?
The plastic circular economy is an ecosystem focused on keeping plastics in productive use for longer through collection, segregation, sorting, mechanical and advanced recycling, and recovery. In the GCC, it connects waste-management systems with recyclers, petrochemical producers, polymer manufacturers, converters, and brand owners to convert plastic waste into reusable feedstock and circular materials.
2. Why is plastic circularity urgent for the GCC?
The GCC has a strong plastics and petrochemicals base, but its downstream plastic waste ecosystem remains comparatively underdeveloped. Low recycling rates, fragmented collection and source segregation, and limited recovery capabilities are resulting in significant value loss through landfilling, inefficient processing, and exports. Strengthening circularity can help the region capture this lost value while reducing dependence on virgin polymers.
3. Can the GCC become a regional hub for circular plastics?
Yes. The GCC has several structural advantages, including established petrochemical infrastructure, polymer manufacturing expertise, deep capital availability, industrial clusters, and access to global trade routes. These capabilities can support the development of integrated recycling systems and advanced recycling capacity, positioning the region to become a hub for circular polymers and recycled materials.
4. Which GCC countries offer the strongest growth opportunities in plastic circularity?
Saudi Arabia, the UAE, and Oman each present distinct opportunity. Saudi Arabia offers significant potential because of its large plastic waste volumes and established petrochemical ecosystem. The UAE is showing stronger momentum in collection, recycling investments, and policy activity, while Oman offers opportunities to strengthen its emerging recycling ecosystem and improve feedstock recovery and domestic utilization.
5. What technologies are shaping the GCC’s circular plastics ecosystem?
Mechanical recycling remains important, while advanced recycling technologies such as pyrolysis and depolymerization are gaining relevance for mixed, multilayer, contaminated, and other hard-to-recycle plastics. AI-enabled sorting, improved MRFs, source segregation, and preprocessing are also becoming important for improving feedstock quality and recovery efficiency.
6. Where are the biggest growth opportunities in the GCC plastic recycling market?
Key opportunities are emerging across integrated collection and advanced sorting, advanced recycling, and circular polymer solutions. Companies that can secure reliable feedstock, integrate recycling technologies, and develop certified recycled polymers are being positioned to capture value as the GCC moves toward more commercially viable circular ecosystems.
Ready to Lead the Transformation?
- Schedule a Growth Strategy Dialog: Align your growth roadmap with Frost & Sullivan’s Visionary Growth Pipeline™ Dialog.
- Engage with Growth Experts: Co-design AI-enabled, data-driven operating models that scale industry-specific and commercial impact.
- Showcase Your Transformational Leadership: Position your organization as a transformation leader through Frost & Sullivan’s Transformational Growth Leadership platform.
- Join the Growth Council: Collaborate with industry leaders shaping the future of your ecosystem.
- Explore Best Practices Recognition: Be recognized for excellence in growth strategy, execution, and customer impact.
- Benchmark Your Industry Positioning on the Frost Radar™: Benchmark your growth performance and innovation strength against industry competitors.
- Tell Your Story: Accelerate awareness, engagement, and revenue growth through integrated brand and demand generation strategies.