This blog is based on Frost & Sullivan’s analysis, “Wood Coatings Market, Global, 2026-2032,” authored by Simran Tamboli, from the Chemicals, Materials, and Nutrition Practice Area.
Executive Summary
The wood coatings market is being shaped by engineered wood adoption, sustainability requirements, premium aesthetics, and increasingly industrialized production models. Waterborne, ultraviolet (UV)-cured, and other advanced technologies are gaining traction, as manufacturers seek coatings that combine durability, design, environmental performance, and production efficiency. These shifts are driving demand for coatings that combine durability, design, environmental performance, and production efficiency, opening new growth opportunities across technologies, substrates, and applications.
The next competitive advantage in wood products may be determined by what goes on the surface. Wood coatings are becoming a strategic factor in durability, aesthetics, sustainability, and manufacturing efficiency as engineered wood gains traction, furniture production becomes more industrialized, and environmental requirements intensify. These shifts are creating demand for substrate-specific formulations, faster-curing technologies, factory-applied finishes, and lower-emission solutions across furniture, cabinetry, flooring, and other applications.
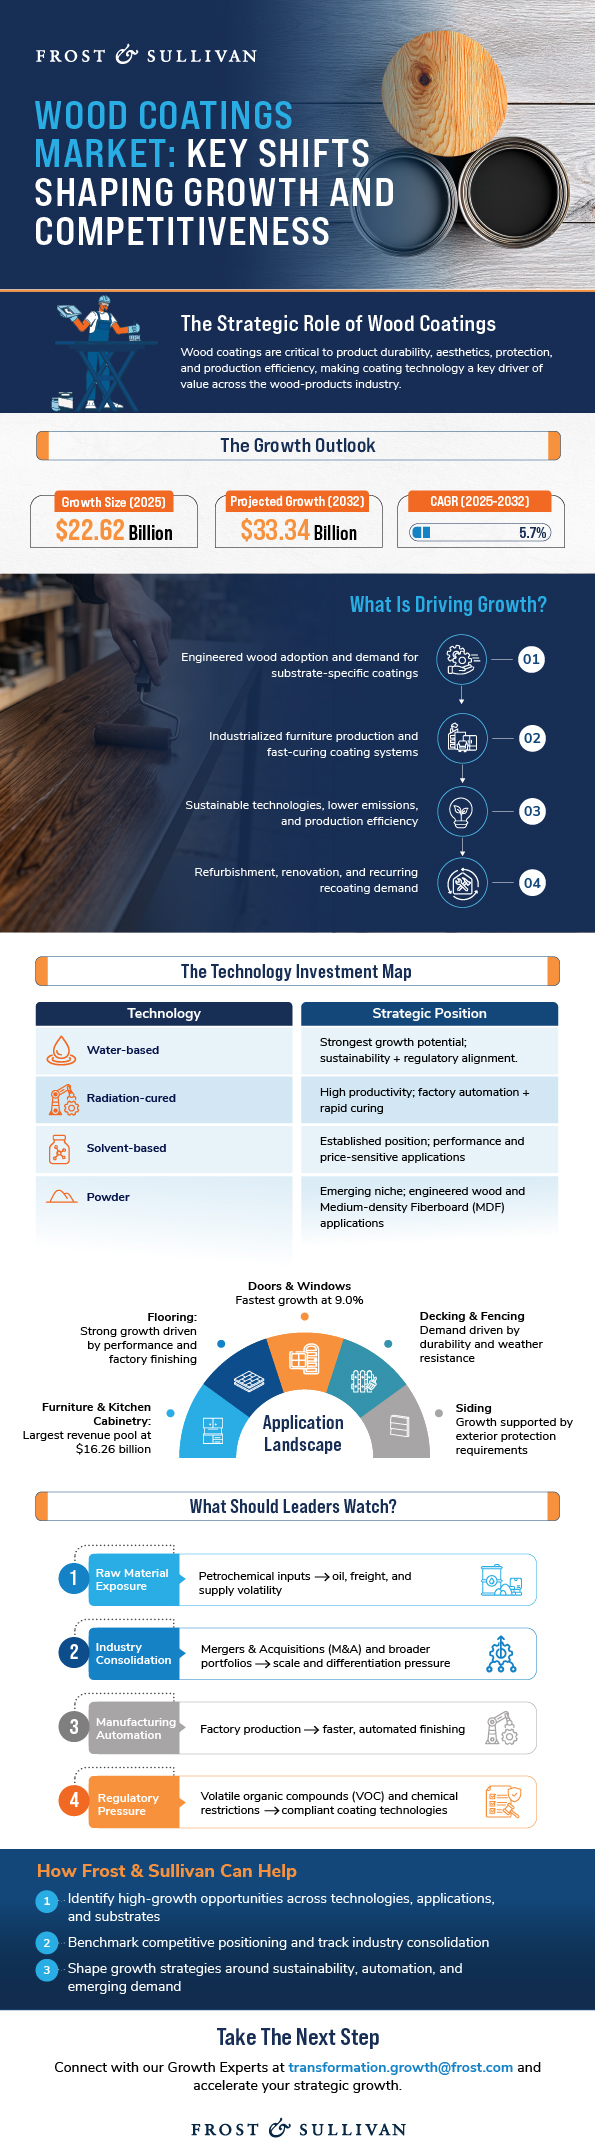
The global wood coatings industry is projected to reach $33.34 billion by 2032. Refurbishment and recoating are adding recurring demand beyond new construction, while waterborne and UV-cured technologies are expanding the solution landscape. For industry leaders, the opportunity is centered on technology differentiation, production efficiency, substrate performance, and sustainable value creation.
Is your wood coatings strategy ready to capture emerging growth opportunities?
Key Takeaways
- The wood coatings market is projected to reach $33.34 billion by 2032, supported by demand for higher-performance and sustainable wood coating solutions.
- Doors and windows are recording the fastest application growth at 9.0%, while furniture and kitchen cabinetry remain the largest revenue segment at $16.26 billion in 2025.
- Asia-Pacific is leading regional demand, with China serving as a major hub for furniture, cabinetry, and wood-product manufacturing.
- Engineered wood and factory-finished production are creating new opportunities for substrate-specific, automated, and high-efficiency coating systems.
- Waterborne, UV-cured, and other lower-emission technologies are creating opportunities where sustainability can be combined with faster curing, durability, and production efficiency.
Tune into our podcast episode on Growth Opportunities in Wood Coatings Market
What Is the Wood Coatings Market?
The wood coatings market comprises protective and decorative solutions that enhance the appearance, durability, and resistance of wood and wood-based substrates. These coatings serve applications such as furniture, cabinetry, flooring, doors, windows, siding, and decking.
The industry spans solvent-based, water-based, radiation-cured, and powder formulations, with demand shaped by engineered wood adoption, sustainability requirements, and evolving manufacturing processes.
How Technology Is Reshaping Wood Coating Performance
Changing substrates, production models, and sustainability requirements are redefining wood coating performance. Here are the key shifts shaping this transition:
|
Dimension |
Traditional Role |
Emerging Performance Requirements |
|
Core function |
Protecting and decorating wood surfaces |
Enhancing durability, aesthetics, and product life |
|
Manufacturing |
Supporting conventional application processes |
Enabling faster, automated, and factory-based production |
|
Technology |
Conventional coating formulations |
Advanced polyurethane, acrylic-urethane, water-based, and radiation-cured systems |
|
Sustainability |
Meeting basic environmental requirements |
Lower-emission technologies and improved environmental performance |
|
Substrates |
Primarily solid wood |
Medium-density Fiberboard (MDF), High-density Fiberboard (HDF), plywood, particleboard, composites, bamboo, and modified wood |
|
Performance requirements |
General surface protection |
Substrate-specific adhesion, moisture resistance, curing, durability, and finish quality |
Reflecting on these shifts, Simran Tamboli, Research Analyst, Chemicals, Materials, and Nutrition at Frost & Sullivan, observes, “The global wood coatings market is moving beyond traditional protective finishes to higher-value systems that improve wood aesthetics, durability and life cycle performance. While overall volume growth remains tied to construction activity, housing starts and furniture demand, the most attractive opportunities are emerging in premium, sustainable and performance-driven coating technologies.”
Strategic Imperatives Shaping the Wood Coatings Industry
- Geopolitical Chaos: Building Resilience Against Raw Material Volatility
Wood coatings depend on petrochemical-derived inputs such as polyols, isocyanates, acrylic monomers, and solvents, exposing manufacturers to fluctuations in oil, energy, and freight costs. Geopolitical disruptions are adding further pressure on supply routes and pricing, making sourcing diversification and regional manufacturing capabilities important considerations for supply chain resilience.
- Competitive Intensity: Competing in a More Consolidated Industry
Consolidation is reshaping the global coatings landscape as leading companies pursue greater scale, broader wood coating technology portfolios, and geographic reach. This is raising competitive pressure across wood coatings while creating differentiation opportunities for regional and specialty suppliers through technical expertise, customized formulations, application support, and niche capabilities.
- Transformative Megatrends: Aligning with Industrialized Furniture Production
Factory-finished, modular, and ready-to-assemble furniture models are changing coating requirements, with manufacturers seeking automated, high-throughput, and fast-curing technologies such as UV-curing systems. This shift is strengthening the connection between coating suppliers and furniture production ecosystems, making automation compatibility and partnerships with OEMs increasingly relevant to competitive positioning.
Download the Full Analysis to Explore More
Regional Growth Dynamics
Wood coatings are evolving differently across regions, shaped by manufacturing concentration, environmental regulations, construction activity, and adoption of advanced coating technologies. These differences are creating distinct opportunities for technology suppliers and manufacturers across Asia-Pacific, Europe, the Americas, and Middle East, Africa, and South Asia (MEASA).
- Asia-Pacific: Manufacturing Scale and Technology Transition
Asia-Pacific remains a major hub for wood coatings, led by China’s large furniture, cabinetry, and wood-product manufacturing base. Solvent-based and polyurethane systems remain prominent, while water-based and UV technologies are gaining relevance. Japan and South Korea maintain technology-driven industries, while Southeast Asia is benefiting from manufacturing shifts.
- Europe: Regulation Driving Technology Adoption
Stringent environmental and chemical regulations are accelerating the shift toward water-based and lower-emission coating systems. Italy and Germany remain important furniture and manufacturing centers, while Eastern Europe is gaining relevance as a production location.
- Americas: Mature Demand and Technology Diversification
The United States represents a mature wood coatings industry, with water-based technologies holding strong relevance. Latin America remains more price-sensitive, with solvent- and oil-based systems maintaining a significant presence, while high-performance wood coatings and sustainable solutions are creating new opportunities.
- MEASA: Construction and Furniture Supporting Demand
MEASA presents a diverse growth landscape, with India emerging as an important demand center supported by urbanization, furniture production, and export activity. Market fragmentation is creating demand for coating solutions that balance affordability, environmental performance, and durability.
Application Landscape: Where Is Wood Coatings Demand Concentrating?
Wood coatings demand is not growing uniformly across applications. Furniture and kitchen cabinetry remain the dominant revenue opportunity, while doors and windows record the fastest growth at 9.0%.
|
Application |
2025 Revenue |
2032 Projected Revenue |
Growth Rate |
|
Furniture & kitchen cabinetry |
$16.26 billion |
$22.78 billion |
4.9% |
|
Flooring |
$2.75 billion |
$4.41 billion |
7.0% |
|
Doors & windows |
$2.05 billion |
$3.75 billion |
9.0% |
|
Decking & fencing |
$1.09 billion |
$1.67 billion |
6.3% |
|
Siding |
$0.48 billion |
$0.72 billion |
6.0% |
Source: Frost & Sullivan, Wood Coatings Market, Global, 2026–2032
The application landscape presents a clear balance between scale and growth velocity. Furniture and kitchen cabinetry remains the dominant revenue opportunity, while doors and windows records the fastest growth at 9.0%, with flooring also demonstrating strong value expansion. This points to differentiated opportunities across both high-volume and faster-growing applications.
Top 3 Growth Opportunities to Watch
- Engineered Wood Coatings
The expansion of engineered substrates is creating demand for specialized coatings that address the distinct performance requirements of MDF, HDF, plywood, particleboard, and composite materials. The opportunity extends beyond basic surface protection toward solutions supporting adhesion, moisture resistance, finishing quality, and manufacturing efficiency.
- Refurbishment and Recoating
Renovation and refurbishment are generating recurring coating demand independent of new construction cycles. Products that simplify preparation and application while reducing drying time and maintaining long-term durability are gaining relevance among contractors, remodelers, and consumers. The segment also creates opportunities for digital retail and contractor-oriented distribution models.
- Sustainable Wood Coating Systems
Waterborne, UV-cured, and other low-emission technologies are gaining traction as sustainability requirements converge with productivity objectives. The strongest opportunity lies where environmental performance can be combined with rapid curing, reduced waste, improved durability, and compatibility with industrial production.
Explore More Growth Opportunities by Downloading the Full Analysis
Competitive Landscape: Scale Meets Specialization
The wood coatings industry remains competitive, with global coatings companies and specialized regional suppliers participating across different applications and geographies.
Sherwin-Williams, AkzoNobel, PPG, and RPM International collectively account for 28.7% of industry revenue, highlighting the presence of large-scale leaders alongside a broad field of specialized competitors.
Companies are differentiating through:
- Tailor-made formulations
- Color and aesthetic diversity
- Advanced durability and performance
- Bio-based and lower-impact chemistries
- Competitive pricing
- Application-specific technical support
- Portfolio breadth and geographic reach
Industry consolidation is also influencing the competitive structure, with acquisitions and partnerships expanding capabilities and geographic presence.
The competitive equation is therefore extending beyond coating chemistry toward scale, technical specialization, customer integration, and innovation capacity.
The Next Phase of Wood Coatings Growth
The next chapter of the wood coatings market will be shaped by solutions that combine advanced performance, sustainable chemistry, substrate compatibility, and production efficiency. Engineered wood, automated manufacturing, advanced curing, and refurbishment will continue creating new requirements for coating technologies across the wood products ecosystem.
Looking ahead, innovation will sit at the intersection of coating chemistry, substrate engineering, and manufacturing technology. Companies that anticipate these shifts and deliver high-performance wood coatings, sustainable, application-specific solutions will be well positioned to capture emerging value across furniture, cabinetry, flooring, and exterior wood applications.
Frequently Asked Questions (FAQs): Wood Coatings Market
1. What are wood coatings?
Wood coatings are protective and decorative finishes applied to wood and wood-based substrates to improve aesthetics, durability, and resistance to moisture, chemicals, abrasion, and environmental exposure. They are used across applications such as furniture, cabinetry, flooring, doors, windows, siding, and decking.
2. How big is the global wood coatings industry?
The global wood coatings industry generated $22.62 billion in revenue in 2025, and it’s projected to reach $33.34 billion by 2032. Demand is supported by furniture and cabinetry production, residential construction, refurbishment, engineered wood adoption, and premium interior applications.
3. What are the top companies in the wood coatings industry?
Leading companies include Sherwin-Williams, AkzoNobel, PPG, and RPM International, which together account for 28.7% of global industry revenue in 2025. Other notable participants include Axalta, Nippon, Kansai, Jotun, Teknos, Renner, and several regional and specialty suppliers.
4. Which region dominates the global wood coatings industry?
Asia-Pacific represents a major regional hub, supported by China’s extensive furniture, cabinetry, and wood-product manufacturing base. Japan and South Korea maintain mature, technology-driven industries, while Southeast Asia is benefiting from manufacturing shifts and expanding production activity.
5. What are the major wood coating technologies?
The major technologies include solvent-based, water-based, radiation-cured, and powder coatings. Water-based and radiation-cured systems are gaining traction as manufacturers address sustainability requirements, VOC reduction, faster curing, productivity, and performance needs.
6. Why is engineered wood driving demand for specialized coatings?
The growing use of MDF, HDF, plywood, particleboard, and composite panels is creating different requirements for adhesion, moisture management, surface preparation, curing, and finish quality. This is supporting demand for coatings designed around specific substrate characteristics rather than generic wood-finishing requirements.
Ready to Lead the Transformation?
- Schedule a Growth Strategy Dialog: Align your growth roadmap with Frost & Sullivan’s Visionary Growth Pipeline™ Dialog.
- Engage with Growth Experts: Co-design AI-enabled, data-driven operating models that scale industry-specific and commercial impact.
- Showcase Your Transformational Leadership: Position your organization as a transformation leader through Frost & Sullivan’s Transformational Growth Leadership platform.
- Join the Growth Council: Collaborate with industry leaders shaping the future of your ecosystem.
- Explore Best Practices Recognition: Be recognized for excellence in growth strategy, execution, and customer impact.
- Benchmark Your Industry Positioning on the Frost Radar™: Benchmark your growth performance and innovation strength against industry competitors.
- Tell Your Story: Accelerate awareness, engagement, and revenue growth through integrated brand and demand generation strategies.